Commercial Property Invoice Coding Workflow for Landlords
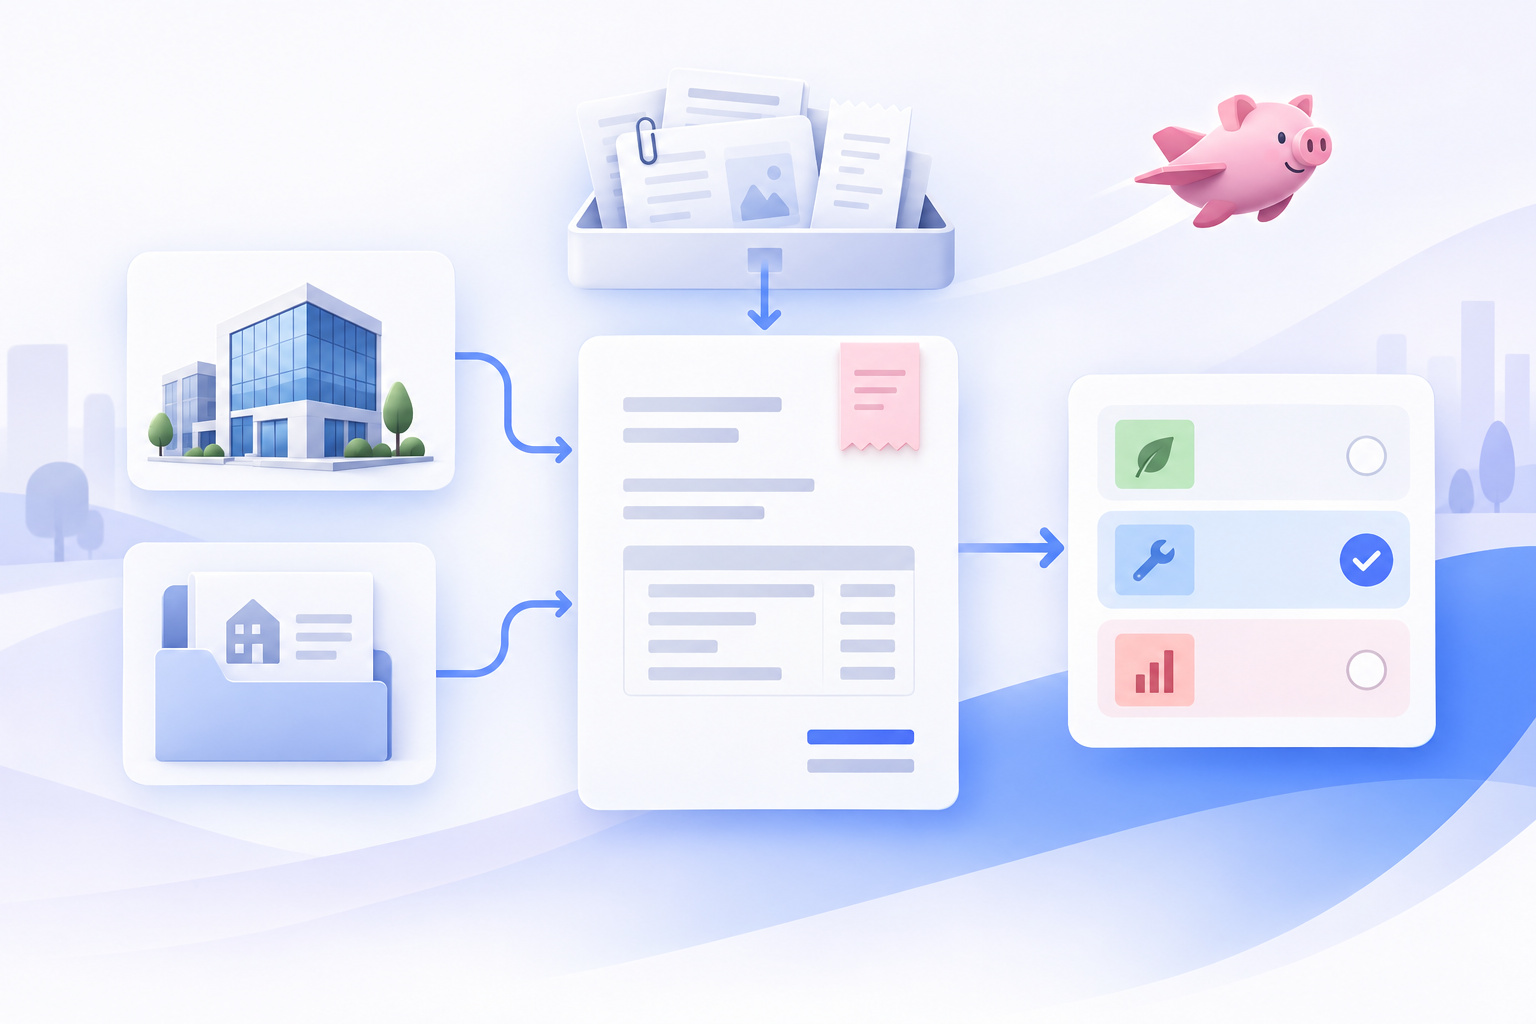
Commercial Property Invoice Coding Workflow for Landlords
An invoice can be perfectly valid and still be hard to use.
A landscaping bill may cover the whole center, but the invoice does not say which areas were serviced. A plumbing charge may be tied to one suite, a common-area line, or an unresolved responsibility question. A utility bill may span more than one building. Months later, when someone asks whether the cost belongs in a CAM pool or why a tenant was charged, the team is left reconstructing the answer from an invoice, an email thread, and somebody's memory.
That is not primarily an approval problem. It is an invoice-coding problem upstream of approval and payment.
For commercial landlords, coding should do more than select a general ledger account. It should preserve the property, area, service period, vendor, source evidence, and any allocation or lease question that gives the charge its meaning. When those details are captured while the invoice is fresh, accounting has a cleaner handoff and future CAM work starts with better records.
This is workflow guidance, not legal, tax, or accounting advice. Lease language, tax treatment, and accounting policy should be reviewed with the appropriate qualified professional for your portfolio.
Why commercial invoices need more than an account code
In a simple business, a vendor name, amount, and expense account may be enough to move a bill through the books. Commercial property creates another layer of questions:
- Which property, building, or suite received the goods or service?
- Was the work for a tenant space, a common area, or both?
- What service period does the invoice cover?
- Is the charge tied to a contract, quote, work order, utility account, or prior repair?
- Does the invoice need to be split across locations, areas, owners, or expense pools?
- Is there a lease-related question that should be visible before the cost is considered for tenant recovery?
If the answer to those questions lives only in a property manager's inbox, the invoice has been coded too lightly. The book entry may be complete, but the operating record is not.
Good source evidence matters outside of any landlord-specific workflow, too. The IRS notes that supporting business documents can include invoices and should identify details such as the payee, amount, payment evidence, date, and description of the purchased item or service.[^1] A commercial property team often needs additional operating context on top of that: where the service occurred, what it served, and what records explain the allocation.
Treat coding as a short intake workflow
The goal is not to turn invoice entry into a long investigation. It is to make the missing context visible while the person who can answer is still easy to reach.
Start each vendor bill with one intake record that keeps the original invoice attached. Then collect the information needed to classify, allocate, and route the item without guessing.
1. Capture the invoice exactly as received
Keep the original invoice or vendor document, including any page that shows the work description, service dates, line items, invoice number, and terms. Record the basic fields first:
- vendor name and invoice number
- invoice date, due date, amount, and service period
- purchase order, contract, quote, work order, or utility account number when available
- payment terms and any early-payment discount
- the person responsible for filling in missing context
This first step helps with duplicate checks, but it also protects the decision trail. If the vendor later sends a corrected invoice, retain the original and connect it to the revision rather than replacing it without a record of what changed.
2. Assign the operating location before the expense account
The first question for most commercial invoices is not "What account is this?" It is "What did this serve?"
Identify the narrowest useful location the available evidence supports:
- property and building
- suite or tenant, when the work is tenant-specific
- common area, parking area, roof, signage, or other shared asset
- portfolio or owner-level activity when it is not property-specific
Avoid guessing from a vendor's name. A familiar HVAC contractor may work at several properties; a single landscaping vendor may bill separate sites under similar descriptions. If the invoice does not establish the location, route it to the person who ordered, observed, or manages the work.
3. Add the service context that explains the charge
Next, capture a brief plain-language description of the work and link the evidence that explains it. Depending on the invoice, that could be a work order, a signed proposal, a service report, photos, a vendor contract, an email authorization, or a utility statement.
The description does not need to be a narrative. It needs to be specific enough that someone reviewing the bill later can understand the connection:
- "Quarterly exterior pest service — common areas, April through June"
- "Replace storefront glass — Suite 204, service report attached"
- "Parking-lot lighting repair — east lot, work order 1182"
For recurring vendors, link the current invoice to the active service agreement and billing period. If the billed scope does not match the agreement or the property team cannot confirm the service, mark that as an exception rather than quietly writing a cleaner description.
Code the cost without deciding every future question
After property and service context are captured, assign the preliminary financial coding required by the portfolio's accounting policy. That may include an expense account, department, owner, entity, project, or other internal field.
This is also the right time to separate three decisions that often get compressed into one:
1. What is the charge for? The operational description and general expense category. 2. Where does the cost belong? The property, building, suite, common area, or owner context. 3. How should the cost be treated later? Any allocation, recoverability, capitalization, or lease-related question that needs a separate review.
Those decisions inform one another, but they are not interchangeable. A cost can be correctly recorded for payment while its tenant allocation still needs review. Likewise, a charge may belong to a property but require a split between a suite-specific portion and a common-area portion.
Use a status such as "lease review needed," "allocation pending," or "contract variance" when the answer is not known. A visible exception is better than a confident-looking code with no source behind it.
Build allocations from evidence, not after-the-fact memory
Some invoices naturally belong to one property and one category. Others need to be divided. The coding record should show both the allocation basis and the source that supports it.
Common allocation situations include:
- one vendor invoice covering several properties
- a utility bill spanning multiple buildings or meters
- a repair with tenant-specific and common-area work on the same invoice
- a service charge that covers a period crossing month-end
- an expense that needs separate tracking for a particular owner, project, or expense pool
For each split, record:
- the total invoice amount
- each allocated amount or percentage
- the destination for each portion
- the basis for the split, such as line items, meter reads, square footage, service dates, contract pricing, or a documented management decision
- the supporting document or calculation
Do not invent precision the invoice does not support. If a vendor combines several jobs into one vague line item, request clarification or document the best available basis and assign an owner for follow-up. The point is not to create a perfect allocation from thin evidence. It is to preserve the reasoning used so a later reviewer does not have to reverse-engineer it.
When the cost may appear in a future tenant charge, retain the allocation source with the invoice record. A year-end reconciliation is much easier to explain when the monthly coding already shows why the expense went where it did. For the later true-up and tenant-facing support, see our guide to building a CAM reconciliation backup package.
Flag lease and recovery questions at coding, not at reconciliation
Invoice entry is not the moment to make every final lease interpretation. It is the moment to prevent lease questions from disappearing.
For a cost that may be subject to pass-through rules, record the question in a structured, searchable way. Examples include:
- common-area versus tenant-specific service
- possible exclusion or cap treatment
- repair versus capital or improvement review
- unusual charge outside the normal service scope
- expense-pool classification
- allocation method that may vary by lease or area served
The label should describe the question, not assume the answer. "Review storefront repair responsibility under Suite 204 lease" is useful. "Tenant recoverable" without a source is not.
This keeps the workflow distinct from CAM reconciliation itself. Reconciliation is where actual expenses, tenant estimates, lease rules, and final calculations come together. Invoice coding is the upstream discipline that makes that later work less fragile.
Keep the coding handoff separate from approval authority
An invoice can be fully coded and still need someone to confirm the work, resolve an exception, or authorize payment. Conversely, an approver should not have to reconstruct the property and allocation context before making a decision.
The coding handoff should give the approver or payment owner a concise record:
- original invoice and linked source evidence
- vendor, invoice number, amount, and due date
- property and area served
- service period and work description
- preliminary expense coding
- allocation detail and basis, if the invoice was split
- open lease, contract, or exception questions with a named owner
Approval authority, payment limits, and escalation rules are separate controls. If you need that part of the process, read our commercial property accounts payable approval workflow. Keeping the two steps distinct lets the coding team supply context without pretending to decide who may release funds.
A practical invoice-coding checklist
Before a commercial property invoice moves to approval or payment, confirm that the record answers the following:
- Is the original invoice attached and readable?
- Have vendor, invoice number, amount, due date, and service period been captured?
- Is the property, building, suite, or common area served identified from evidence?
- Is there a clear work description and a linked contract, work order, quote, service report, or other source when available?
- Has preliminary accounting coding been assigned according to the portfolio's policy?
- Does the invoice need an allocation, and is the basis for that split documented?
- Are tenant-specific, common-area, and unresolved portions separated rather than blended together?
- Has any lease, recoverability, contract, or capitalization question been flagged with a named owner?
- Can the next reviewer understand the charge without searching multiple inboxes?
Make the invoice useful before it becomes urgent
The best time to capture property and lease context is when the invoice arrives, not when a bill is overdue or a tenant asks about a charge months later.
A consistent coding workflow gives landlords a cleaner payment handoff today and a more useful record tomorrow. It does not replace lease review or professional accounting judgment. It makes the facts and source evidence available to the people who need to apply that judgment.
PigJet helps commercial landlords keep property records, lease context, vendor documents, and follow-up work connected. If invoices are still moving through inboxes without enough operating context, explore a one-property PigJet pilot to test a clearer workflow.
[^1]: Internal Revenue Service, What kind of records should I keep?. This general recordkeeping reference is not tax advice for your specific situation.